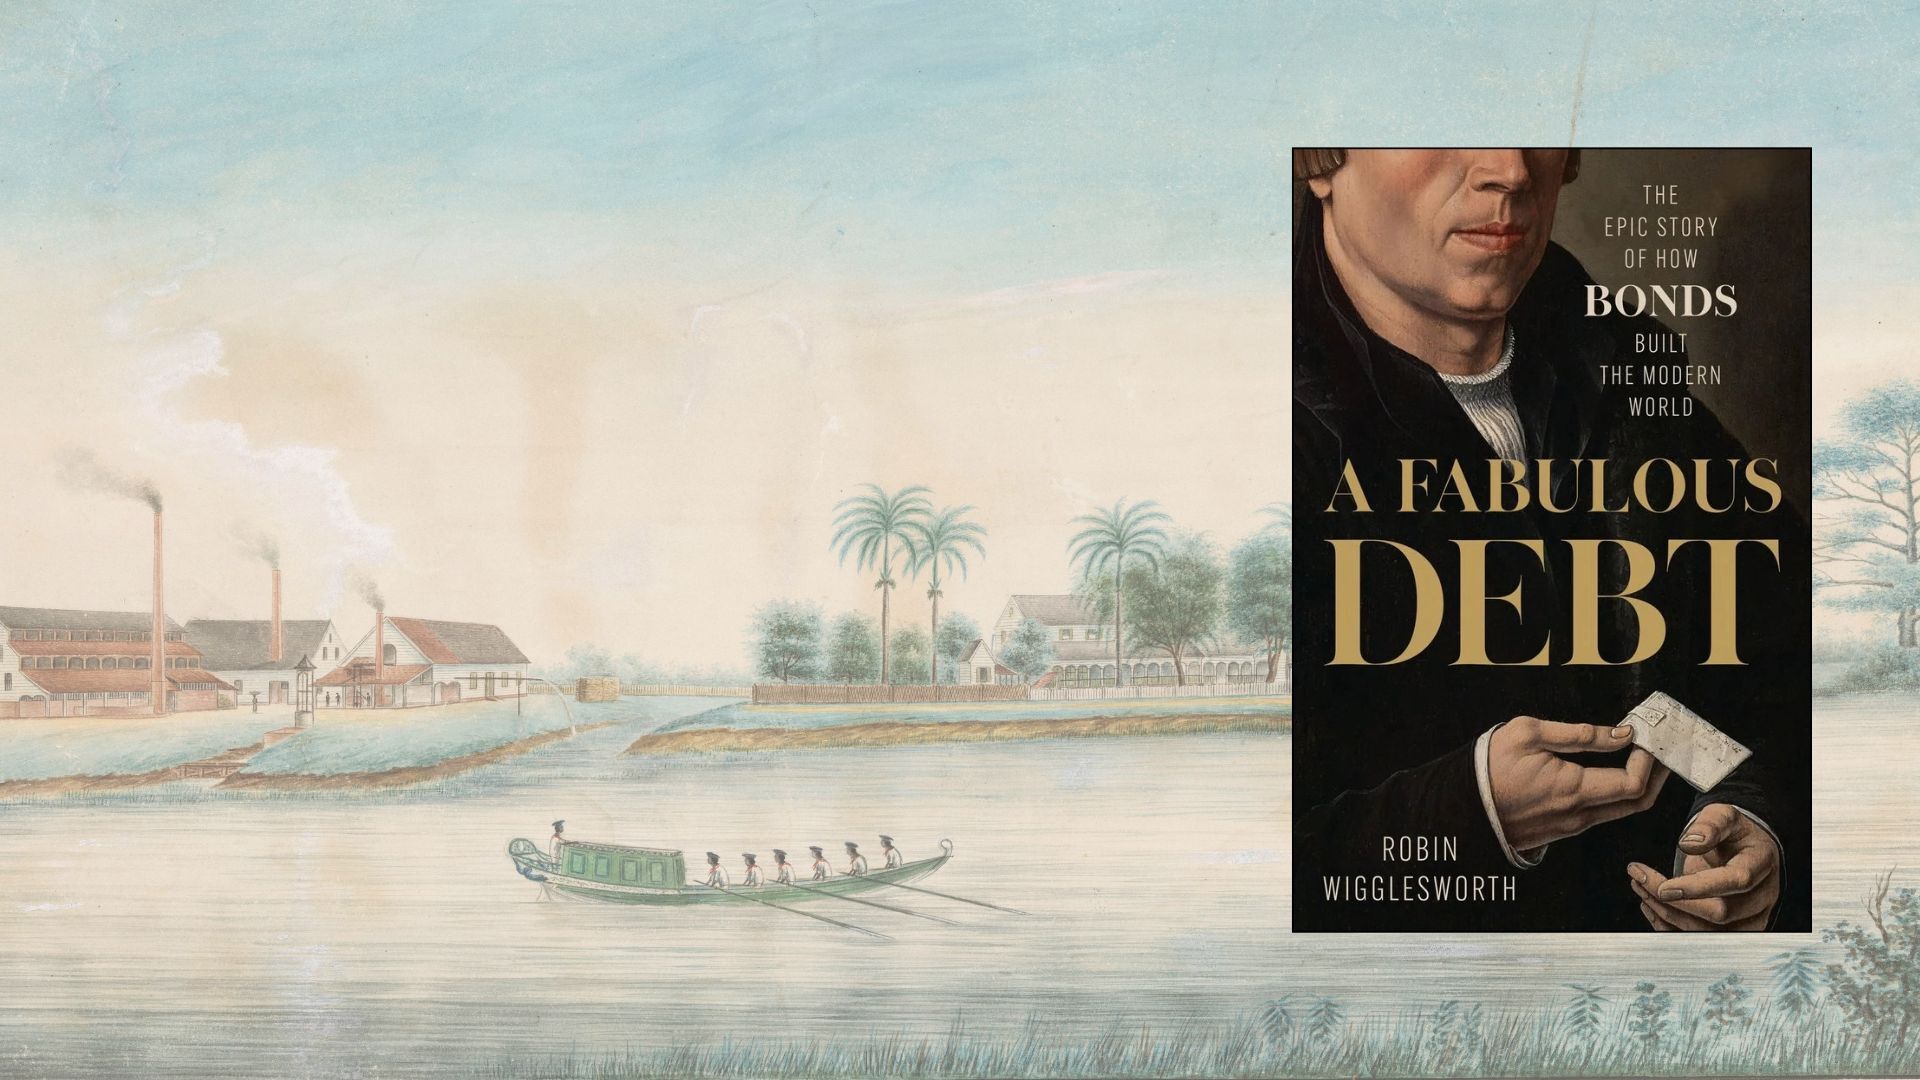
It turns out you can trace America’s 2008 financial crash, in a roundabout way, to 18th-century Prussia. The Seven Years’ War left the kingdom in financial shambles: Just to afford the fighting, Prussia’s king, Frederick the Great, had hired private minters to ramp up currency production. So in 1769, Frederick the Great landed on a novel strategy to keep money flowing into his borders. He organized cash-poor nobles into cooperatives, and began offering, to the highest bidders, bonds based on the value of their land. European investors snapped them up, giving Prussia the injection of cash it needed. It was, as the journalist Robin Wigglesworth writes in his new book, A Fabulous Debt: The Epic History of How Bonds Built the Modern World, possibly the world’s first mortgage bond sale.
A Fabulous Debt is a rollicking look at the development of the bond market, perhaps the least appreciated—but, Wigglesworth convincingly argues, the most important—financial market in the world today. Wigglesworth connects overzealous use of bonds both to the Great Recession and to America’s massive ballooning $40 trillion national debt. Paired with another recent book, David I. Backer’s As Public as Possible: Radical Finance for America’s Public Schools, which chronicles the crushing consequences of the bond market on public schools, a picture emerges of bonds as a little-noticed, and increasingly popular, lever for inequality.
Whether we realize it or not, bonds interlace nearly every facet of our lives. They are basically IOUs that pay out on fixed terms, and that governments and other large institutions issue to raise money. If you have an investment portfolio, it probably contains a slice of bonds sold by the U.S. Treasury. The interest rates of Treasury bonds tend to define the entire market: when the Federal Reserve raises interest rates on its long-term bonds, as it did recently, your auto lender and your credit card company will probably soon hike their rates, too. But bonds show up in increasingly far-flung corners of the economy, too. Bonds likely fund your local public school or bridge improvement project, and they facilitate the resale of your home mortgage. Summer camps issue bonds to raise money, and so do hospitals and local, state, and national governments. All kinds of consumer debts can be re-packaged as bonds, and sold to ever more distant bidders.
Mortgage-backed bonds are among the most enduring, and riskiest, bond structures. Throughout the 18th century, just as mortgage-backed bonds injected cash into a flagging Prussian economy, they also funded colonial conquest. The Dutch leveraged bonds to finance a new crop of coffee and sugar plantation experiments in colonial Suriname, where thousands of enslaved people from Africa were forced to work. The banks decided to make long-term, 20-year mortgage loans to white colonial planters—but, leery of betting too much on these untested entrepreneurs, they decided to spread around the risk. They bundled up all of these plantation loans and resold them as bonds to wealthy investors across the Netherlands. What this meant was that Dutch bankers could quickly recoup their investments, while more risk-tolerant investors held out, hoping for the promised 5-6 percent annual returns on the bonds. Colonial conquest was proving to be highly profitable; investors thought the good times would never end.
In the U.S., where local governments and private companies alike built factories, canals, railroad, and telegraph lines with the money they raised from bond sales, mortgage-backed bonds made an early splash, too. Many of America’s skyscrapers were funded with mortgage-backed bond sales, including the Waldorf Astoria and the Chrysler Building. After collapsing during the Great Depression, mortgage-backed securities started to make their comeback in 1970, when the government-owned corporation Ginnie Mae sold the first modern mortgage-backed security. Soon after, investment bankers began bundling together increasingly risky mortgage loans and reselling them as bonds—often many times, to institutional buyers that had increasingly little relationship to the original home borrower. This kind of reckless profiteering was one of the main drivers of the 2008 financial crash, and it was only possible, perhaps, because of the unique ways that bonds estrange investor and borrower: turning real people’s loans into an abstracted product to be bought and sold, with little consideration for the financial or personal devastation that a default would create.
Today, the arbiters of the bond business are Moody’s, Standard & Poor’s, and Fitch, the Big Three rating agencies that assess the credit of any company, nonprofit, or public institution putting up a bond for sale. These agencies quite literally give your school district or utility company a letter grade: a triple-A rating means they can sell their bond at low interest rates, since there’s so little risk that the bond issuer will default, while a Ba rating means investors might only be willing to buy their bonds at double-digit interest rates. Over time, these interest rates compound exponentially: A low-rated school district, for instance, will pay much more over the lifetime of a bond than a high-rated one.
The powers these companies have amassed is a bit mind-boggling to trace back. Moody’s, which began in April 1909 as a printed manual called Moody’s Analyses of Railroad Investments, assigning letter ratings to railroad bonds, hardly had the powers of mysticism: The company failed to predict the 1929 financial crash, Wigglesworth writes, and dismissed the subsequent stock sell-off as “nothing more or less than a speculator’s frenzy of fear.” No matter, the federal government endorsed Moody’s ratings anyway. In 1936, in order to prohibit banks from making risky investments, the Office of the Comptroller of the Currency issued a proclamation banning “speculative investment securities,” as defined by “recognized rating manuals”—meaning, eventually, Moody’s, S&P, and Fitch. You may also remember the limits of the rating agencies’ oracular powers during the 2008 financial crisis, when they were revealed to have endowed an increasingly risky set of mortgage-backed bonds with sterling credit ratings, right up until the crash.
A bond rating can have immense impacts on an institution’s finances. Differential credit ratings help explain, for instance, why the school district of Paterson, New Jersey—with 95 percent students of color—spends 60 percent more on meeting its debt payments than the majority-white district next door in Fair Lawn. While race and politics are not an input in Moody’s calculations, the company’s rating system tends to produce racialized outcomes: The UCLA professor Justin Gustave McBride recently sampled the credit ratings of small cities and towns across California, and concluded that, the larger the white population in a municipality, the better credit rating they received. In 2018, for instance, Moody’s explained that it cut the credit rating of the majority-Black city of Jackson, Mississippi because of the “low wealth and income indicators of residents.”
Political leaders, too, are often hamstrung by the demands of bondholders and credit ratings agencies. Chagrined by the socialist policies of Zohran Mamdani, New York City’s municipal bondholders—who own $125 billion of public debt used to fund schools, roads, and bridges—have expressed ire at the new administration. The MTA, for instance, funds its improvement projects through the issuance of municipal bonds, many of which are backed by the fares that passengers pay every day. Conservative scholars insist that Mamdani’s promise to make MTA buses free would violate the city’s bond covenants. It would also complicate future bond sales. That, and a little kick in the pants from Moody’s: this past spring, the credit rating agency downgraded the city’s financial outlook to “negative,” meaning the Mamdani administration will probably need to pay higher interest rates the next time it needs to raise money.
Many people hear about the stock market every day, but news about the bond market only seems to reach most of us when something goes wrong: the yield curve inverts, or investor jitters push the interest rates above 5 percent, as is happening as we speak. Even in less volatile times, however, bonds hardly deserve their reputation as staid, safe financial instruments. Since the 1970s, many investors have traded bonds as quickly as stocks, and used them as the springboard for increasingly risky financial experiments. One of those experiments was engineered by an investment banker named Michael Milken, who, in the early 1970s, had the idea of buying up bonds from institutions that Moody’s and other rating agencies insisted were not creditworthy. To account for the fact that they were risky investments, these companies needed to offer their bonds at high interest rates. That meant, for a savvy investor, there was a lot of money to be made if the company repaid down the line. While most institutional investors steered clear of “junk bonds,” Milken started shoveling money into them, buying up low-rated bonds, which he branded as “high-yield,” from a number of failing companies.
By 1977, Milken controlled as much as a quarter of the high-yield bond market, and corporate raiders like Carl Icahn, who specialized in hostile takeover bids of flagging companies, began using Milken’s promise to sell junk bonds as part of their takeover efforts. A letter from Milken promising to find buyers for the junk bonds could justify regime change at a major company with shaky finances. Unsurprisingly, experimentation with risky bonds soon became a tool of private equity companies, which often finance their takeover bids of struggling companies with the promise of high-yield bond sales. In June 2007, for instance, KKR funded a takeover of the credit card maker First Data with $8 billion in junk bonds. That Milken was eventually indicted for securities fraud in 1989 did not slow private equity’s enthusiasm for junk bonds. Neither, frankly, did research showing that private equity bonds tend to underperform the rest of the market.
Other bond innovations that Wigglesworth chronicles in A Fabulous Debt include currency swaps and interest rate swaps, the latter of which involves two companies exchanging their payment obligations. These trades exploded in popularity in the 1980s and 1990s—though they could sometimes end catastrophically, such as when Orange County, California went bankrupt in 1994. Interest rate swaps, of course, meant both parties would remain on the hook for repayments—but other bond hawkers invented financial products that would excise the risk of default entirely.
In 1989, an Exxon supertanker crashed into a reef off of Alaska, spilling, in total, 11 million gallons of oil. Exxon, suddenly on the hook for the cleanup cost, asked its two primary bankers, JPMorgan and Barclays, for $4.8 billion in credit. These banks didn’t want to turn down a major customer—but the returns they would make, if any, on Exxon, which had a stellar credit rating, were minuscule. That money would be far more profitable if it was moved elsewhere, into higher-yield investments. What JPMorgan decided to do was disentangle the economic risk of the loan to Exxon. It asked for the European Bank for Reconstruction and Development to insure it against the remote possibility that Exxon would not fully repay the loan, in exchange for JPMorgan paying the bank an annual fee. This was called a credit default swap: the bank freed up the billions it was lending to Exxon, because it now had a guarantee that the EBRD would repay it in the case of a default.
What emerges throughout A Fabulous Debt, which succeeds in finding the energy and zaniness in a part of the financial world most people probably would not associate with “fun reading,” is a story of investors inventing increasingly complex bond structures like this in order to further estrange themselves from the actual risks, and machinery, of making an investment. A deal between Exxon, JPMorgan, and the European Bank for Reconstruction and Development probably feels distant to most of us, but the same logic of spreading around risk is applied to the payments we make every month on our home or credit cards. When you take out a loan on your car, for instance, that loan rarely resides for long with the institution who issued it to you. More likely, it is packaged up with other loans into a bond, and then sold and re-sold many times, to a set of owners who know you only as a slice of a collateralized credit rating. Whatever the risk is that you might not pay is diluted through financial engineering.
This strained relation to finance, and to the risk of default, explains the continued functioning of certain puzzling sectors of the fintech world. For instance, you might wonder how Americans are ever going to pay back the $157 billion they owe in buy-now, pay-later loans used to cover rent, electricity, luxury goods, and concert tickets. The answer is they might not—but buy-now, pay-later companies have already used the cleansing powers of the bond market to turn a profit on your debt. The private equity firm KKR regularly buys up loans from PayPal, for instance, while Affirm sells loans to New York Life and the investment firm Sixth Street. Klarna, meanwhile, has pawned off $26 billion of BNPL loans, as bonds, to the student loan behemoth Nelnet.
All of this doesn’t mean much for those of us who owe thousands of dollars to a buy-now, pay-later company. That debt is real for us—and so are the consequences of not paying it. But, through the bond market, the person who greenlit the loan might have already made their money back on it. They won’t be the ones holding the bag if everything collapses.